Browsing:

Month: October 2026

Fertile Window and Cycle Tracking in Malaysia: A Plain-English Guide

A person writing notes on a desk calendar with a pen

Your cycle is a pattern, not a calendar promise

Many couples in Malaysia start trying for a baby armed with one rule they heard somewhere: ovulation happens on day 14. For some people it does. For many others it does not, and cycles that vary by a few days each month are completely normal. Treating the cycle as a pattern to understand, rather than a fixed date, takes a lot of pressure off.

A menstrual cycle runs from the first day of one period to the day before the next. Ovulation, when an egg is released, usually happens roughly two weeks before the next period starts, not two weeks after the last one began. That small shift in thinking explains why counting from the wrong end so often misses the mark. For a reader-friendly breakdown in Malay, a cycle and fertile-phase guide written for Malaysian readers walks through the phases step by step.
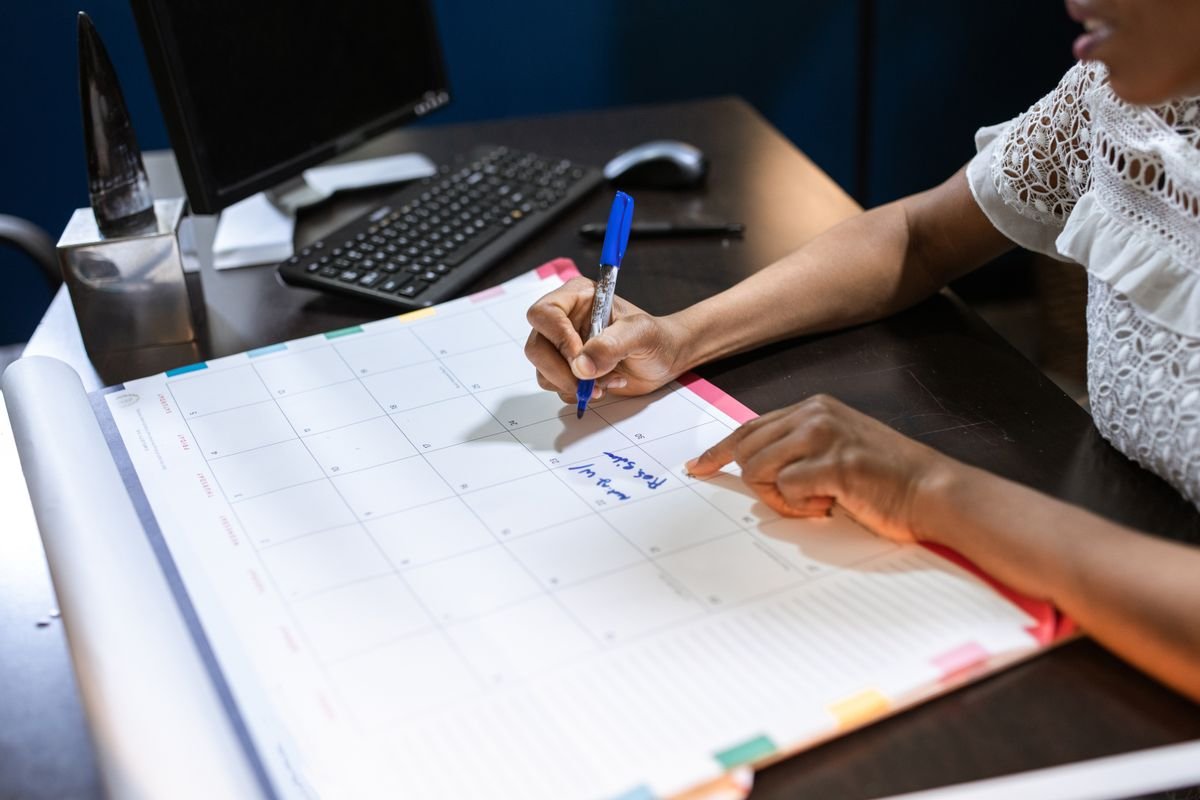
A person writing notes on a desk calendar with a pen
A simple written log of period dates often reveals more than guessing from memory.

Finding the fertile window without an app obsession

The fertile window is the few days leading up to ovulation plus the day of ovulation itself. Sperm can survive for several days, while the egg lasts around a day, which is why the days before ovulation matter most. The NHS page on fertility in the menstrual cycle explains this timing clearly.

There are a few common ways to spot it. Some people notice clearer, stretchy cervical mucus as ovulation approaches. Others use ovulation test kits from the pharmacy, which detect a hormone surge. Basal body temperature charts show a small rise after ovulation, which is better for learning your pattern over months than for timing in the moment.

A fertility doctor explains ovulation, the fertile window and the main ways people track their cycles.

Apps can help with record keeping, but their predictions are only as good as the data you give them. Many doctors simply suggest regular intimacy every two to three days through the cycle, which avoids turning every month into a stressful project.

When cycles are irregular, PCOS is one possibility

If periods are very irregular, very far apart or missing for months, ovulation may not be happening regularly. Polycystic ovary syndrome is one of the most common reasons. It can also bring acne, extra hair growth and weight changes, though not everyone has every sign. Some health services now use a newer name for the condition, so do not be thrown if you see different labels online.

The US Office on Women’s Health PCOS page gives a balanced overview of symptoms and how it is diagnosed. For a local explainer, an explainer on PCOS causes and signs covers the basics in Malay. PCOS is manageable, and many people with it go on to conceive, but it deserves a proper medical assessment rather than guesswork.

Drinks, hydration and what pregnancy actually needs

Once pregnancy is confirmed, or while trying, many women get flooded with advice about special drinks. Water remains the foundation. Milk and other calcium sources, plus a balanced diet, matter more than any single product. Caffeine is usually advised in moderation, and herbal mixtures should be checked with a doctor or pharmacist first.
A pregnant woman sitting by a window holding a glass of water
Plain water and regular meals do most of the work. Special drinks are optional extras.

If you are curious what is commonly suggested, this round-up of pregnancy drinks lists familiar options. Read it as ideas to discuss with your antenatal team, not a prescription.

When to stop tracking alone and ask for help

Fertility takes time even for healthy couples. As a general guide, it is sensible to see a doctor after a year of regular trying, or sooner if the woman is in her mid-thirties or older, cycles are very irregular, or there is a known health issue. Male factors account for a significant share of difficulties, so both partners should be part of the conversation. The WHO fact sheet on infertility explains how common these challenges are worldwide.

Bring your notes: cycle lengths, any test kit results and questions you want answered. A few months of honest records usually make that first visit far more useful.
Malaysian SMEs: Seek Advisory Before Jumping to Loans

The loan-first reflex among Malaysian SMEs

When sales feel promising, many Malaysian SME owners open a financing form before they open a spreadsheet. The instinct is understandable. Growth needs cash, banks and development finance institutions advertise facilities, and waiting can feel like leaving demand on the table. The quieter question is whether the business yet knows what the money must do.

The practical question for many Malaysian SMEs is timing: when business advisory tends to help before you jump straight into a loan application, and what advisors usually clarify before expansion financing. Soft citations point to public pages you can re-read later.

Five professionals collaborating around a wooden table and sticky-note corkboard in a bright modern office

Two common routes. Clarifying cash, purpose, and capacity first usually beats fixing a weak application later.

What business advisory usually clarifies first

Advisory is not a magic stamp of approval. At its best it is a structured pause: diagnose the cash reality, name the financing purpose, and test whether the company can service new obligations without starving operations. Owners who sell well but still scramble for payroll often need diagnosis more than a larger facility.

Typical clarifications sound plain. Are receivables stretching because customers pay late, or because pricing and costing are soft? Is the squeeze seasonal working capital, equipment, a new outlet, or owner drawings mixed into company cash? Public pages on SME business advisory services often frame that work as explore, advise, and connect: assess needs, map eligible options, then introduce financing partners. Treat those steps as a checklist you can run even before any formal meeting.

Also separate capacity building from the loan conversation. Accounting habits, digital tools, and a cleaner set of management accounts do not replace financing, but they make applications less painful and reduce the chance you borrow to paper over a process problem.

When a commercial loan still makes sense

Advisory first does not mean never borrow. A commercial loan can be the right tool when the purpose is clear, repayment is modelled against realistic cash inflows, and the facility type matches the job. Working capital for a known receivables cycle is different from term financing for machinery. Mixing both into one vague “growth loan” is how interest and covenants start fighting the business.

Before you compare rates, write a one-page purpose note: amount, use of funds, expected cash release date, and what happens if sales lag by two months. Then scan public overviews of commercial loan financing the way you would scan a product catalogue: features and eligibility cues, not a verdict. Bank Negara Malaysia’s map of financing support for SMEs is a stable place to see how bank financing sits beside development funds, microfinance channels, and advice touchpoints.

If debt already feels heavy, pause the expansion story and seek education or counselling channels such as AKPK financial counselling rather than stacking another facility on hope.

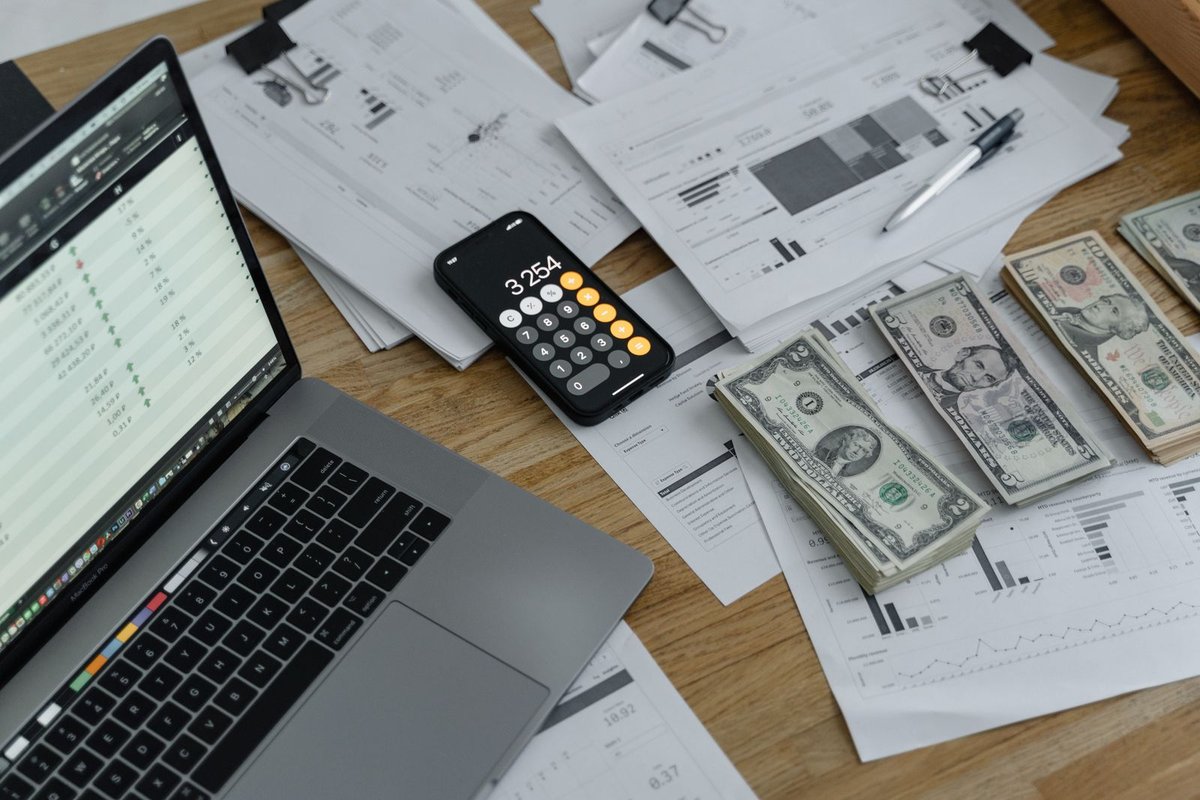
Wooden desk with laptop spreadsheet, phone calculator, banknotes, and financial chart printouts

Three questions before expansion money: cash truth, purpose fit, and capacity to repay.

Expansion financing needs a plan, not a wish

Business expansion financing is attractive language. It can also hide three different jobs: opening another site, entering a new channel, or buying capacity to fulfil existing orders. Advisors press on unit economics for the new step, management bandwidth, and whether the existing core is already cash-stable. Expanding a fragile base multiplies the fragility.

A useful pre-loan pack is modest. Latest management accounts, a 13-week cash view, a simple use-of-funds table, and assumptions you can defend without marketing adjectives. When you later review pages that discuss business expansion financing, you will already know which facility shape fits: shorter working-capital style support versus longer-term funding tied to assets or a defined project.

For a clean refresher on why profit and cash diverge (the gap that sinks many expansion stories), this beginner walkthrough of the cash flow statement is worth a pause before you size any facility:

Related watch: a plain-language cash flow statement primer before you fund expansion on paper profits.

Public maps for advice and financing in Malaysia

Malaysia already publishes touchpoints so owners need not guess alone. SME Corp’s MSME Hub advisory overview describes where enterprises can seek business counselling and programme information. Pair that with BNM’s SME financing page for the lender and fund landscape, and keep Product Disclosure Sheets for any facility you shortlist.

This month, try a small pass. Write the financing purpose in one sentence, sketch thirteen weeks of cash, and only then decide whether you need advisory clarity, a commercial facility, or a staged expansion plan. Malaysian SME growth feels less frantic when the question leads and the loan follows.